Cotton T-Shirts From India by Town, Border Duty and Testing
Where Indian cotton T-shirts are made, what Australia, NZ, the UK, US, EU and UAE charge on them, which origin proof you need and what to test first.
14 min read
What each way of paying an overseas supplier actually protects, from advance wires and deposits against a bill of lading copy to documentary collections, letters of credit, open account and platform payments. India is the worked example, with a first-order payment plan and the Indian export rules that apply from 1 October 2026.
In March 2026 an Indian exporter posted a question most buyers never get to hear. A US customer, a regular for more than three years, hadn't paid for over a year. "Now the buyer is saying to accept 80% loss he can pay only 20%" (r/exportersindia, 2026 (opens in a new tab)). The replies from other exporters were blunt. "Unless it's a Fortune 500 company, never export without payment" (r/exportersindia, 2026 (opens in a new tab)).
That thread is why your Indian supplier asks for half the money up front, and it's also why you're right to hesitate. Both of you are being sensible. This guide explains what each payment method actually protects, whose risk it moves, and what a bank does and doesn't check, with India as the worked example. The caveat - a payment method can move risk around, but it can't make a bad supplier good or a slow buyer fast, so pair it with the checks on verifying Indian suppliers.
Last researched 25 September 2026 · Next review 1 October 2026 · Written by SourcingFrom
You pay and nothing ships. The goods ship and they're wrong. Or you don't pay, and the exporter is left with a container sitting at your port. Every payment method is really a decision about which of those three you carry and which the exporter carries. No method removes all three, whatever the brochure says.
An Indian export adviser summed it up in September 2026 - "Don't confuse a payment term with payment security" (r/exportersindia, 2026 (opens in a new tab)). A term says when money moves. Security is what happens when one side doesn't perform. Keep the two apart and the rest of this guide falls into place.
Here's the rule that runs under everything below - money should move only when something you can verify has happened. A signed PO, an approved pre-production sample, a passed inspection, a bill of lading. If a payment has no event attached to it then it's a gift with a hope attached.
An advance protects the exporter completely and protects you not at all. A wire can't be pulled back once it lands, and buyers who paid through Wise have found the same - "Wise afaik doesn't allow you to reverse a transaction if the seller [doesn't] hold up their end" (r/smallbusinessuk, UK buyer, 2026 (opens in a new tab)). The only protection in an advance is its size and the account it goes to.
So why do Indian makers ask for so much? Partly the thread we opened with. And partly because their own money is tied up before yours arrives. A merchant exporter buys from farmers or small factories who sell for cash, so "I also have to pay farmers or manufacturers in advance, because they don't work on credit" (r/exportersindia, Indian agri exporter, 2025 (opens in a new tab)). Your advance becomes the working capital that buys your goods. That's cash-flow logic, and it's not a warning sign on its own.
It is negotiable, though, and by more than most guides admit. A trade-finance banker puts the usual range at "10-20% advance" (r/exportersindia, 2026 (opens in a new tab)), and another voice in the same thread says 20 to 30% depending on trust. One first-time castings maker shipped three containers to a Dubai buyer on payment against delivery, because "no one was ready to pay advance" (r/IndiaBusiness, 2025 (opens in a new tab)). A buyer with options pays less than the 50% everyone quotes.
Two rules make an advance safer without making it smaller. Pay only a corporate account in the exporter's registered legal name, matched to its GST record and its proforma invoice, never a director's personal account or a "sister firm". And size the advance to what it buys - materials and set-up, yes, the whole order, no. An advance that funds the purchase of finished stock tells you you're dealing with a trader financing the deal with your money. That's a normal model, and one you should know you're in.
This is the most common middle ground with Indian suppliers, and the least understood. You pay a deposit, the goods ship, the exporter emails a copy of the bill of lading, and you wire the balance.
The copy proves that a carrier received a sealed container and, if it's an on-board bill, that it's on the ship. It doesn't prove what's inside. If you pay the balance against the copy alone then you've paid for a box, not for goods.
The fix is cheap. Make the balance depend on two documents arriving together - the clean on-board bill of lading copy and a pre-shipment inspection report from an inspector you appointed. The inspection happens before the container is sealed, so the two documents describe the same goods, and now the copy proves shipment while the report proves contents. Quality control in India covers how to book that inspection.
From the exporter's side this method carries its own fear - goods on the water, a silent buyer, and a container running up demurrage at a foreign port. The thread at the top of this page is that fear come true. Answer it in writing by naming the release trigger, the bank and the day. And if the exporter keeps the original bills of lading until the balance clears, that's fair. Whoever holds the originals controls who collects the goods.
A collection puts a bank between you and the exporter as a courier for documents. The exporter ships, hands the shipping documents to its bank, and that bank sends them to yours. Your bank releases them against payment (documents against payment, D/P) or against your signed promise to pay on a date (documents against acceptance, D/A). Without the bill of lading you can't collect the container, so the goods stay under the exporter's control until you act.
The rules are the ICC's Uniform Rules for Collections, URC 522, and the bank's job under them is narrower than most buyers think. Banks "will not examine documents", have "no obligation to store and insure goods", and must act in "good faith and reasonable care" (ICC, URC 522 (opens in a new tab)). The bank checks that the listed documents are present. It doesn't check that they're right.
D/P tells you the goods have shipped before you pay, and tells the exporter you can't collect them until you have. It doesn't protect quality, because you pay before you open the box, but add your inspection report to the document list and it does. D/A leaves the exporter carrying your credit, which is why a small Indian exporter will rarely offer it to a new buyer.
D/P is the term Indian exporters actually settle for. One exporter's advice to his peers was "Push for Advance and settle not below DC (DP)" (r/exportersindia, 2026 (opens in a new tab)). If you won't open a letter of credit, D/P is the floor most small exporters will accept, and it's far lighter on paperwork.
A letter of credit is your bank's promise to pay the exporter when it presents the documents the credit names, in the form the credit describes, by the date the credit sets. The rules are the ICC's UCP 600 (ICC, UCP 600 (opens in a new tab)).
Two of its articles explain nearly every LC dispute. Article 4, "Credits v. contracts", means a credit "has its own terms and conditions which do not rely upon the terms or performance of the sales contract" (ICC Academy (opens in a new tab)). Article 5, "Documents v. goods", means the bank pays against paper. If the documents comply, the bank pays even if the goods are wrong. If they don't, it can refuse even if the goods are perfect.
So an LC protects the exporter's payment first, which is why a banker tells Indian exporters "If you are dealing with new buyers better to insist on an lc" (r/exportersindia, 2026 (opens in a new tab)). For you it protects document discipline, and that's worth more than it sounds. If the credit requires an inspection certificate from an agency you name, the exporter can't be paid without passing your inspection.
Exporters resist LCs on cost and speed - "Opening an LC means they have to pay around a percentage of the invoice to the bank" (r/exportersindia, 2026 (opens in a new tab)). Our view is simple. An LC earns its keep on a first large order and on anything made to your design. On a repeat order of stock goods it's usually an expensive way of saying you don't trust someone. And an LC without an inspection certificate in its document list is a promise to pay for paperwork.
You get the goods, then you pay, on 30, 60 or 90 days. It protects you and exposes the exporter, which is why it only arrives with a track record or an insurer behind it. In India the state export credit insurer sets a limit per overseas buyer, so an exporter who says its insurer won't cover you means it doesn't hold a limit on your company yet. How that works is on MOQ, pricing and payment in India.
The law sets the outer edge. Under India's new export regulations, in force from 1 October 2026, an exporter must realise the export value within 15 months of shipment, or 18 months if the invoice is in rupees (Regulation 5, RBI FEMA 23(R)/2026-RB (opens in a new tab)). It's a generous edge. Indian law isn't what keeps terms short, the thread at the top of this page is.
Buyers who learned sourcing in China expect a marketplace to hold the money. For a foreign buyer in India that layer is thin, and the platforms' own terms show where it stops.
IndiaMART's Buyer Payment Protection Plan, in force since 12 February 2026, is domestic only, covers complete non-delivery only, and lists "Foreign buyer transactions" among its exclusions. It "does not constitute an insurance contract, escrow mechanism, financial guarantee" (IndiaMART (opens in a new tab)). The older "Pay with IndiaMART" gateway was "discontinued permanently" on 31 March 2024 (IndiaMART FAQ (opens in a new tab)). So any supplier offering it is describing something that no longer exists.
Alibaba.com is the exception, for some sellers. Since 30 June 2025 it offers Trade Assurance to Indian suppliers who opt in, with your money held until you confirm receipt (Alibaba.com, 30 June 2025 (opens in a new tab), Supplier-stated). It covers only those sellers and only payments made on Alibaba. Before the launch, buyers on forums reported India-based sellers asking for PayPal or a wire because Alibaba payments did not work in India, and a seller who still asks you to pay off the platform leaves you uncovered. Most Indian suppliers list on IndiaMART instead, which excludes foreign buyers. More in is there a Trade Assurance for India? PayPal Goods and Services is the usual first-order method for small buyers, and one US buyer described using it "for the first few buys and then wire once we have a relationship" (r/ecommerce, 2020 (opens in a new tab)). But in disputes over goods from India, "PayPal denied my case and said I had to pay to return the item" (r/Etsy, 2023 (opens in a new tab)). Fine for samples. Not a guarantee for an order.
And a supplier-proposed "escrow"? An escrow you didn't choose, run by a company you can't check, is a payment to a stranger. A real one has a licensed operator, published terms and a release condition you wrote.
Read the "bank checks" column before you choose anything.
| Method | Your main risk | The exporter's main risk | What the bank checks |
|---|---|---|---|
| Advance by wire | Money gone before goods exist | None | Nothing |
| Deposit plus balance on B/L copy | Paying for a sealed box, not its contents | A silent buyer and demurrage | Nothing |
| D/P collection | Paying before you open the box | You refusing at the port | Documents are present, not correct |
| D/A collection | Little, once you hold the documents | Your credit | As above |
| Letter of credit | Paying for compliant paper, unless inspection is a required document | Discrepancies that delay payment | Documents against the credit, never the goods |
| Open account | Little | Everything | Nothing |
A bank never checks goods. Only an inspector does, and only if you appoint one.
Say you're a Melbourne importer buying 4,000 cotton T-shirts from a Tiruppur maker, FOB Chennai, first order. Here's a plan that puts each risk on the side best placed to carry it.
The deposit funds the maker without funding the whole deal, the inspection makes the final payment mean something, and D/P keeps the exporter in control of the goods until you pay, which is what it wanted all along.
On a second order of the same style, shrink the advance. By the fourth, ask for open account and expect the insurer question. For a first order made to your own design, swap D/P for a letter of credit that lists the inspection certificate as a required document. Then run the whole order through the landed cost calculator, because a plan that protects you still has to add up.
Ready to act
Need hands-on help?
Staged payments only work if someone checks each milestone before the money moves. SourcingSync sets up the milestones and holds the supplier to them.
India's new export regulations bind the exporter and its bank, not you, but they set the edges of what your supplier can agree (RBI FEMA 23(R)/2026-RB (opens in a new tab), read 25 September 2026). Four clauses matter to a buyer.
Export proceeds must be realised within 15 months of shipment, or 18 if invoiced in rupees (Regulation 5). A third party can pay only where the exporter's bank "is satisfied with the bonafides" (Regulation 8), so paying from your group company or a financier is the bank's call, not your right, and you should agree it before the PO. An advance and the later proceeds must route through the same bank (Regulation 10). And an exporter with proceeds unrealised beyond a year past due "shall undertake further exports only against receipt of full advance or an irrevocable Letter of Credit" (Regulation 13). If a supplier will only take advance or an LC, that may be why, and it's worth asking about, kindly.
We re-check this on 1 October and quarterly after that. The full clause table is on MOQ, pricing and payment in India.
New bank details by email are the oldest fraud in trade and still the most effective. Confirm every change by voice on a number you already held, before any money moves. The controls are on risks of buying from India.
Fee escalation after the deposit is the other classic. A "minimum order" top-up, then a "customs" fee, then an "export" fee, each small enough to feel cheaper than walking away - one buyer "paid over 500$ and he shipped 10$ of the product and is asking for large sums of money from me now" (r/IndiaBusiness, 2026 (opens in a new tab)). The all-in price was agreed before the deposit. A fee that isn't on that page ends the deal.
And many small parcels cost your supplier more than you'd think. Small Indian exporters pay their bank to close each shipping bill, and one handicraft exporter said "Trying to close 2000+ shipping bills which are B2C is a nightmare" (r/StartUpIndia, 2025 (opens in a new tab)). Expect them to price that in or to steer you towards one consolidated shipment.
It's safe for the exporter's payment and for your documents. It doesn't check the goods. Add an inspection certificate from your nominated agency as a required document and it protects both sides.
Common, especially from merchant exporters whose own suppliers want cash, and negotiable. Trade-finance voices put typical advances at 10 to 30%. Pay it to a verified corporate account and size it to materials.
Not on IndiaMART, whose plan excludes foreign buyer transactions in its own terms. On Alibaba, yes, if the Indian seller has opted into Trade Assurance (available since 30 June 2025) and you pay on Alibaba. A payment made off the platform isn't covered.
Only if the exporter's bank is satisfied with the transaction's bona fides, under Regulation 8 of the RBI's 2026 export regulations. It's the bank's call, so agree it before the PO.
The exporter in our opening thread had done everything on trust, with a buyer he'd known for three years, and it still went wrong. The adviser's line fits him exactly - a payment term isn't payment security. The same is true in reverse for you. A 50% advance to a maker you've never checked isn't security either, however friendly the emails are.
The middle ground is where good long relationships with Indian suppliers actually start. A modest deposit to a verified account, an inspection you control, and a balance released against documents both of you can see. Once each side has seen the other perform, the terms loosen on their own.
The payment clause itself, milestones and the named-bank rule are on MOQ, pricing and payment in India. Related guides: import duty, certificate of origin, sea freight routes, supplier payment disputes, why Indian suppliers ask for full advance.
Where Indian cotton T-shirts are made, what Australia, NZ, the UK, US, EU and UAE charge on them, which origin proof you need and what to test first.
Want new guides when they go up? Get the newsletter
Leave your email and the PDF downloads straight away. We don't email it to you.
An Indian proforma invoice is the supplier's written offer, and it is usually what you pay a deposit against. Before paying, check that it carries the legal name exactly as on the GST record, the GSTIN and an export code that is the same PAN, your full spec and quantity, an HS code, an Incoterm with a named place, payment terms tied to events, and a bank account in that same legal name. An export invoice should not normally add Indian GST, so a tax line is a question to ask.
Indian suppliers often ask for 100% advance on a first order because small makers lack working capital and your money pays for the materials. It is not a red flag on its own, and it is negotiable. A letter of credit, documents against payment or a deposit tied to inspection can replace much of the advance.
Don't pay until you've confirmed the change by phone on a number you already had, never one from the email that brought the news. Then check that the new account is in the supplier's GST legal name, ask why it changed, and ask for a letter from the bank. Indian exporters must update bank details on their export code within 30 days of a change, so a genuine supplier should have the paperwork to show you.
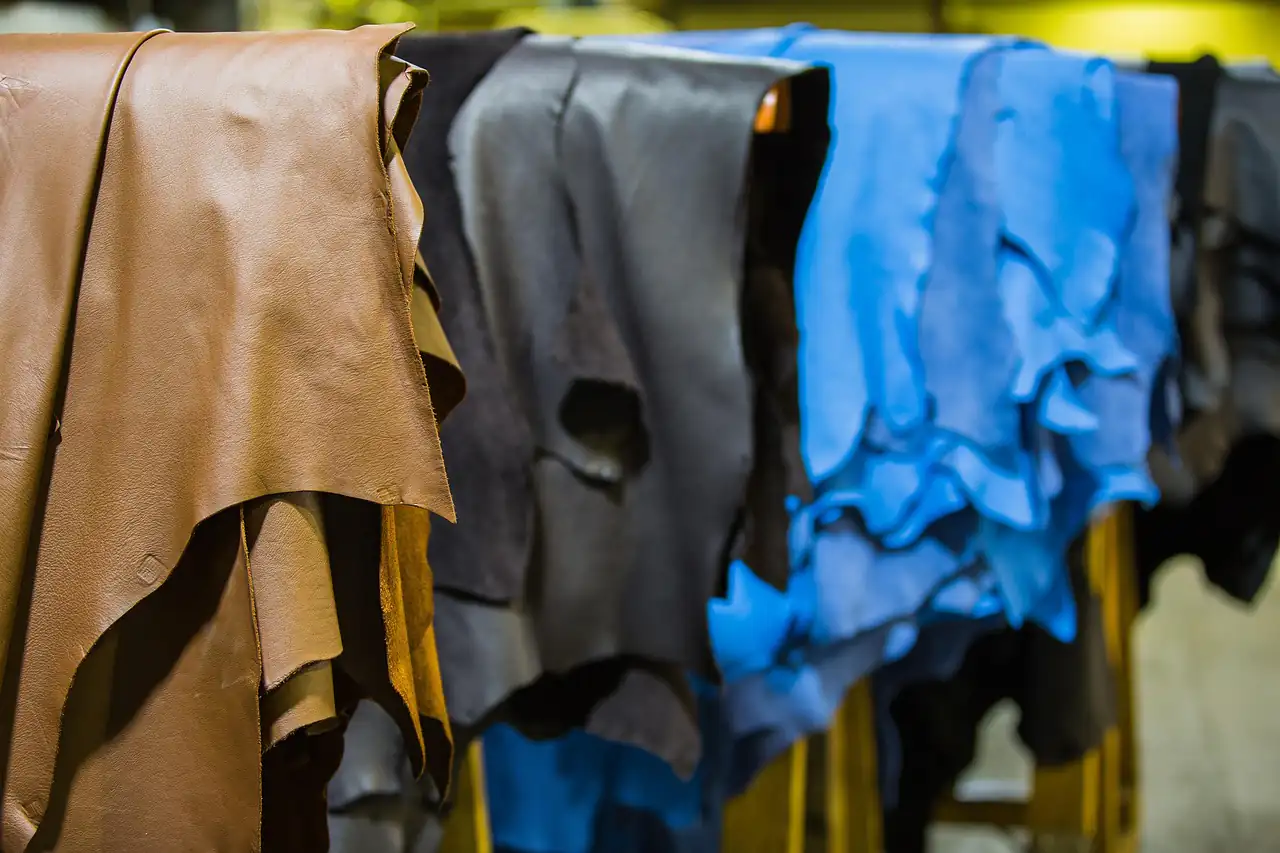
A quote that says "leather" tells you nothing about the animal, and in India the answer is often goat, sheep or buffalo rather than cowhide. Each behaves differently in a bag: goat is tough and small, sheep is soft and delicate, buffalo is thick, coarse and variable. Ask for the species, the tannage and the tannery in writing, check the grain yourself, and sample buffalo from the actual lot.
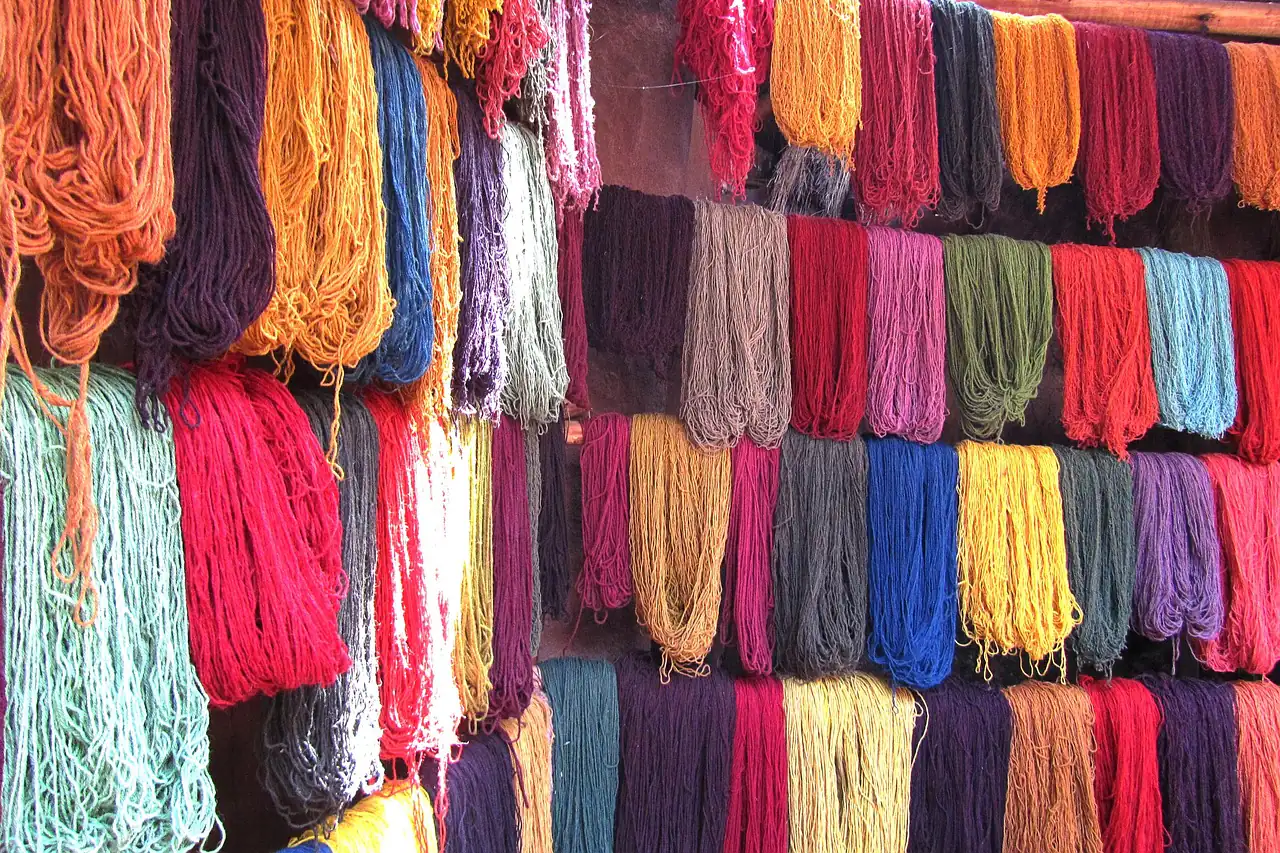
A custom rug from India usually arrives off-colour for one of five reasons: the colour was approved on a screen, the bulk yarn went into a different dye lot, the yarn looks different once woven into pile, the post-weaving wash shifted it, or it is being judged in different light or from the other end of the pile. Each has its own approval. Because returning a large rug to India is slow and costly, the approvals and the remedy belong in the order before weaving starts.
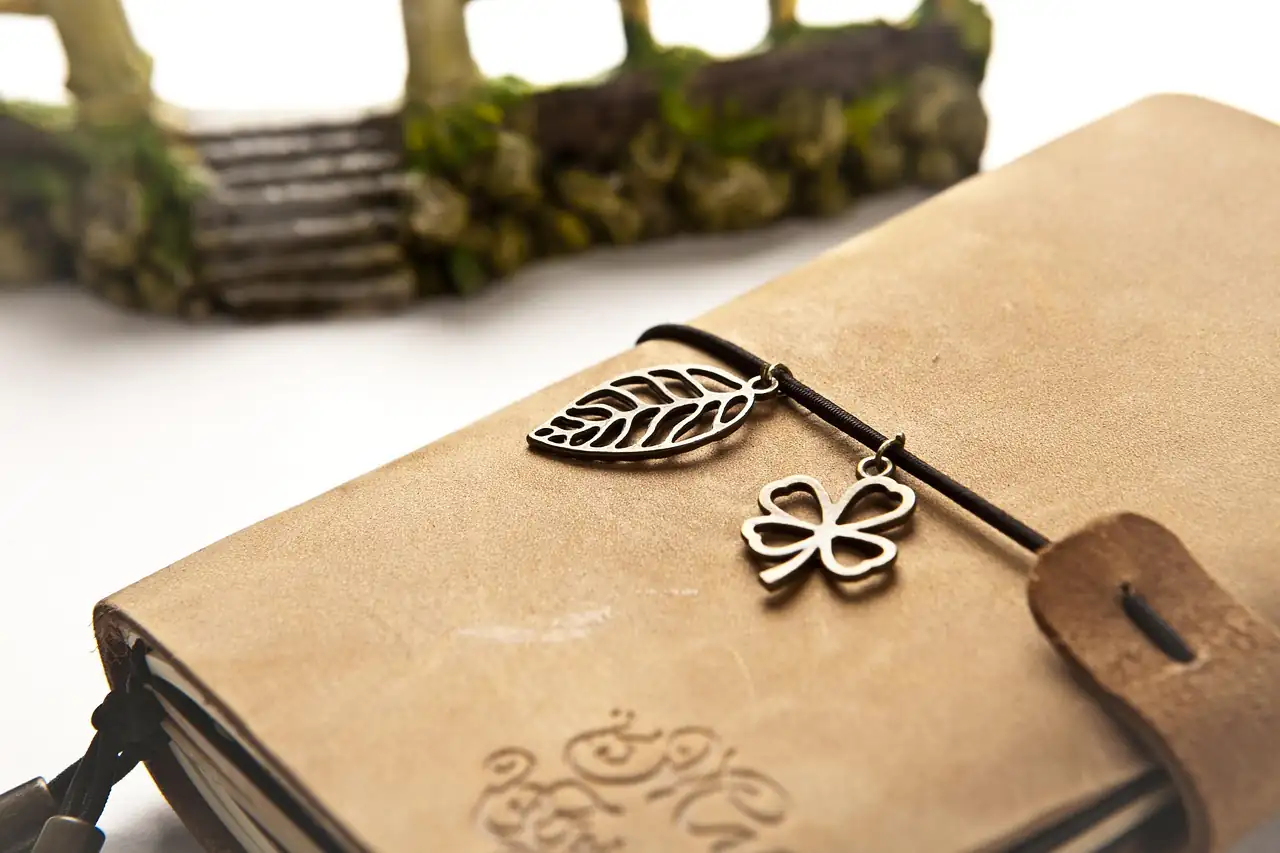
No. Urine does not tan leather, and the smell some buyers notice on Indian leather has ordinary causes: tannery residue left by poor washing and finishing, solvent finishes and bag-making glues, and moisture in packing and transit. Each smells different and has its own fix. Odour has no legal limit, so it has to go into the spec, with a closed-box check on bulk before you accept a shipment.